When I invited questions on my Instagram account, I was not simply looking for questions to answer. I wanted to understand what was on people’s minds, particularly friends and colleagues working in real estate brokerage, and hear perspectives that might challenge my own. Some of those questions touched on issues I had been considering but had not yet discussed openly.
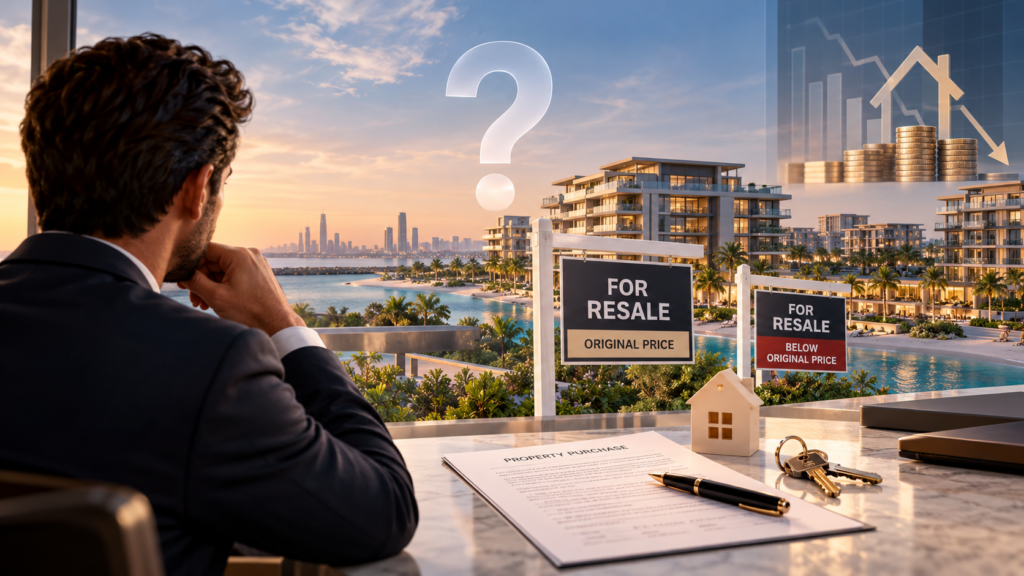
One issue deserves a candid conversation: properties being offered for resale at their original purchase price, and sometimes below it. I have encountered such listings in Abu Dhabi, including on Fahid Island, across Fahid Beach Residences, Fahid Beach Terraces, and The Beach House Fahid, the names used in Aldar’s official sources.
These are observations from my work in the market, not a comprehensive statistical survey. An asking price is also not necessarily a completed transaction price. Nevertheless, the situation raises an important question: does an owner seeking to exit at the original price reveal a weak project, or a weak investment plan?
When a quick resale becomes the only plan
In some cases we have encountered, the buyer did not enter with an investment strategy suited to the project. The plan was much simpler: buy at launch, wait for the price to rise, and sell before a later instalment becomes due.
That expectation can sound convincing when investors hear about profits others made in earlier launches. It becomes even more persuasive when a broker reinforces it, and the buyer then arrives at a crowded launch event.
But a busy launch does not guarantee that someone will buy your particular unit six months later at the price you need. Strong primary sales for a developer and liquidity in the resale market are different things. Resale liquidity means finding a buyer within your required timeframe and at an acceptable price.
A profit made in an earlier project does not establish a rule for the next one. Entry prices, supply, unit characteristics, competition, and market timing may all differ. We also tend to hear more about exceptional profits than about owners who waited much longer or exited without a gain.
A quick resale is possible. It is not guaranteed. The problem begins when an optimistic possibility becomes the only way the purchase can be funded.
Believing in Fahid is not the same as treating it as a six-month trade
My long-term conviction in Fahid Island’s potential has not changed. Aldar unveiled the island’s masterplan in June 2025, presenting it as an integrated coastal destination between Yas and Saadiyat islands, with residential, educational, retail, and leisure elements planned within the development. Fahid Beach Residences was the first residential development announced within that masterplan.
In my view, investing in a new destination of this scale differs from buying within an established, mature community. You are not only buying a unit. You are also investing in the development of its surroundings: facilities being delivered, services becoming operational, residents moving in, and genuine demand forming for ownership, renting, and resale.
That is why I personally approach Fahid with a five-to-seven-year horizon from launch. This is my investment perspective, not a developer-issued delivery schedule, a guaranteed maturity date, or a promise that prices will rise. Some investments may require a longer holding period, depending on execution, demand, and market conditions.
It does not mean that everyone who sells earlier is wrong, or that an early profit is impossible. It means that buying a long-term development with money you need back within months exposes you to substantial risk.
Nor does a strong project make every unit suitable or every price attractive. Entry price, views, layout, payment terms, costs, and competing supply all affect the quality of the investment. The same principles apply elsewhere, but the appropriate holding period will not be identical for every project.
Why might an owner sell at the original price or below it?
In real estate, as in other financial decisions, someone may sell an asset at its original purchase price or below it for reasons connected to their life, financial capacity, strategy, or the asset itself. A lower priced exit is not always a forced loss. It can be a deliberate decision to release capital or reduce risk.
The table below sets out possible reasons and connects them to the points I have raised about some resale situations on Fahid Island. These are potential explanations, not a diagnosis of every seller or a statistical ranking of causes.
| Possible reason | Why might it lead to a sale at the original price or below it? | Connection to the points I have raised |
|---|---|---|
| Personal or family circumstances | Health needs, relocation, separation, or an estate settlement may make access to cash more important than waiting for a higher price. | An independent reason for selling that does not necessarily indicate a weak project or poor original advice. |
| Changes in income or business needs | Reduced income or a business need for liquidity may limit the owner’s ability to hold the investment. | Pressure can arise after a sound purchase; not every seller initially bought to speculate. |
| Repaying debt or reducing financing commitments | An owner may accept a lower price to reduce obligations and avoid their continuing costs. | Reinforces the need to assess the full financial position, not just affordability of the initial payment. |
| Portfolio reallocation or another opportunity | An investor may prefer to release capital or reduce concentration rather than wait for a gain on this asset. | An exit at the purchase price can be a considered investment decision, not a verdict that Fahid has failed. |
| Inability to fund construction instalments | An approaching unfunded payment can shift the priority from making a profit to finding a buyer quickly. | Directly reflects my concern about buyers who funded the first payment and depended on resale to cover later commitments. |
| No workable plan for the final payment | Without adequate liquidity or a feasible financing plan, an owner may seek an exit before the obligation falls due. | Reflects my warning to plan for the final payment from the outset, rather than rely on a possible sale or uncertain financing. |
| A quick profit as the only strategy | If the expected resale does not happen within months, the buyer may accept an exit without the anticipated profit. | This is central to my criticism of the promise to buy now and sell in six months, particularly when the buyer cannot wait. |
| Copying others’ profits and following launch excitement | Success stories and crowded launches can encourage buying without an independent assessment of price, liquidity, and risk. | Connects to my concern about applying earlier launch experiences to Fahid and treating crowds as proof of guaranteed profit. |
| Unsuitable broker advice or unrealistic promises | A client may take on an obligation that does not fit their capacity or horizon when profits are promoted without the risks. | Connects to the role of some brokers who prioritise closing the transaction over assessing suitability. |
| Selling before the community develops and wider demand forms | In a developing destination, the owner may not yet find demand at the expected price, particularly when a quick sale is needed. | Illustrates the mismatch between my longer investment horizon for Fahid and an exit strategy measured in months, without guaranteeing later gains. |
| Competition from developer stock and resale listings | Comparable alternatives and attractive payment terms can reduce a seller’s ability to command a premium. | Explains why a successful initial launch does not establish that every unit can easily be resold at a profit. |
| A high entry price or a less attractive unit | Views, layout, or the purchase price may limit buyer interest compared with alternatives. | Reinforces that confidence in the project does not make every unit or entry price a suitable investment. |
| Genuine demand weakness or development risks | Weaker demand, delays, or changing project expectations may prompt a price reduction or a decision to reduce exposure. | Must be assessed using evidence, not assumed from a single listing or dismissed because of my conviction in the project. |
In the cases I am discussing, several factors may overlap: an expectation of a quick sale, reinforced by someone else’s experience or a broker’s advice, followed by an instalment without sufficient funding. When these factors combine, a lower asking price can reflect a fragile purchase strategy rather than provide sufficient evidence of project failure. Personal changes or portfolio decisions, however, may explain a sale even when the original purchase plan was sound.
Another misconception needs correcting: selling at the original purchase price does not necessarily mean breaking even. Depending on the transaction and contract, the seller may incur fees, commissions, financing costs, or transfer expenses. True break-even requires comparing the full cost of the investment with net sale proceeds, not simply comparing two headline prices.
A promoter is not necessarily an adviser
Brokers have considerable influence over buyers’ expectations. With that influence comes considerable professional responsibility.
Telling a buyer, “Purchase now and sell at a profit in six months,” without a defensible basis or a clear explanation of timing risk, weaker demand, and resale conditions is not responsible investment advice. Presenting a possibility as a guarantee is misleading, and the desire to close a deal does not excuse it.
The problem becomes deeper when brokers are trained to overcome objections but not to assess suitability. Not every concern is an objection to defeat. Some concerns are genuine warnings that the purchase does not fit the client.
I am not describing all brokers. Many provide excellent advice and protect clients from unsuitable decisions. However, in cases I know, unrealistic expectations encouraged by some brokers were an important factor in investors’ plans coming under pressure.
A good adviser asks: can you continue making payments if we do not sell? How will you fund the final payment? Could you hold the property if your exit takes longer than expected? That adviser must also be willing to say, “This is a good project, but it does not suit your current financial plan.”
The buyer has responsibilities too. Poor advice does not remove the need to read the contract, understand the obligations, and assess affordability. Some losses may also arise from changing market conditions or development risks rather than brokerage alone.
What buyers should arrange before signing
Start with the most important question: if I cannot sell when I expect to, can I still meet my commitments?
Establish a clear funding plan for every construction instalment and the final payment, with an emergency reserve. If you expect to obtain financing at handover, do not treat future approval or an anticipated bank valuation as guaranteed.
Review the resale and assignment conditions in your contract, including any approvals, payment requirements, or associated charges. Being able to advertise a property does not necessarily mean you can complete a sale immediately.
Compare your unit with genuine alternatives. Ask the broker to distinguish advertised prices from verified transaction prices and explain the basis for expecting a future buyer. Then test your plan against a delayed sale, no price growth, or a longer holding period than you originally intended.
Your investment should not depend on the best-case scenario being the only scenario that occurs.
How an individual experience can become a misleading market verdict
When someone buys on the promise of a quick profit and then has to exit at the original price or below it, frustration is understandable. But that owner may tell friends that “the market is bad” or “the project has failed,” when a significant part of the problem may lie in the advice received or a purchase strategy that did not match their financial capacity.
In this way, expectations that were unrealistic from the outset can damage confidence in the market. Brokers should take that consequence seriously: the impact of their advice does not end when the commission is paid.
At the same time, this explanation must not become an excuse to ignore genuine weakness in prices, demand, or execution. Assessing a market requires actual transactions, available supply, the pace of sales, and development progress, not a single success story or a single loss.
A project can be good while the strategy used to invest in it is wrong. Your conviction in a project can also be sound while your ability to hold the investment is insufficient.
Luxury off-plan real estate is not a promise that a small initial payment will produce an exceptional profit and an immediate exit. Responsible investing starts with understanding what you are buying, why you are buying it, how you will fund it, and what you will do if the outcome you hoped for does not materialise.
A genuine adviser measures success not only by closing the transaction, but by whether it was suitable for the client who placed their trust in them.
References
The sources below substantiate project names and the masterplan announcement. Resale observations, assessments of some brokers’ conduct, and the investment horizon represent the author’s experience and opinion, not statistical findings published by Aldar.